Mapping Service Team Processes to Credit Decision Rules in Transnational Subscription Charge Systems
Petra Lorenz · Sep 21, 2026
Mapping Service Team Processes to Credit Decision Rules in Transnational Subscription Charge Systems
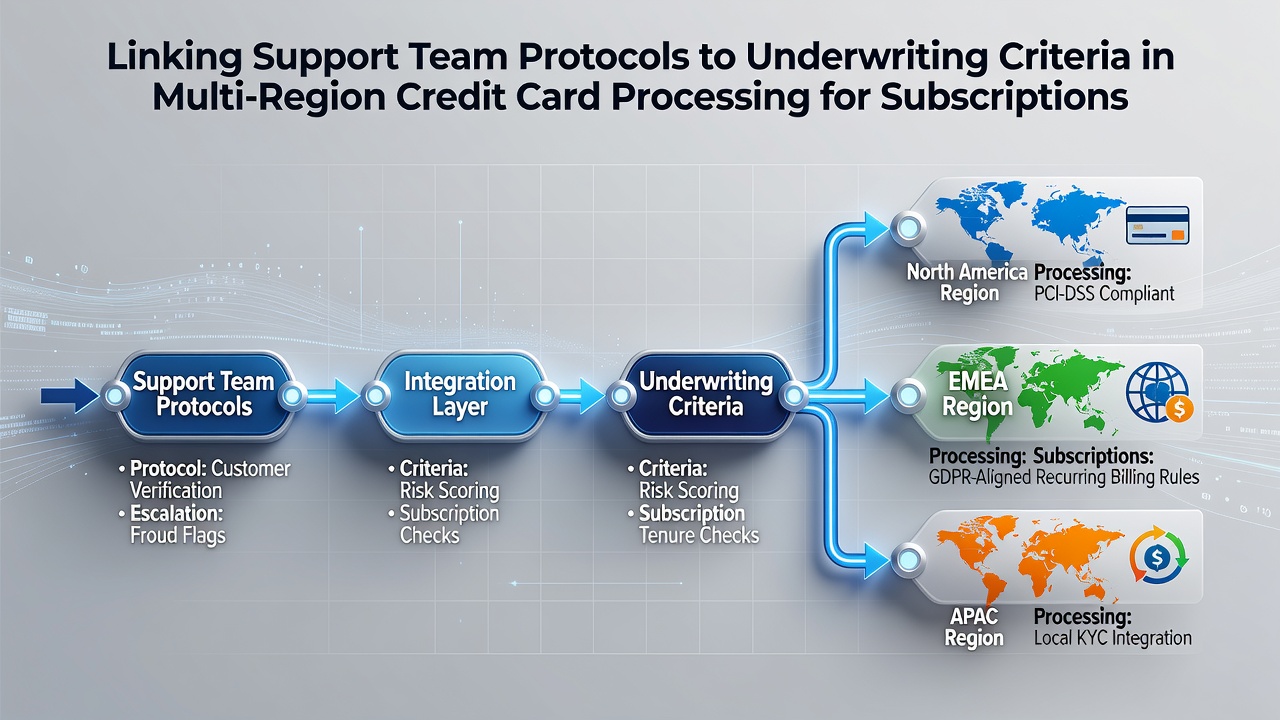
Support team protocols and underwriting criteria intersect at multiple points when organizations handle credit card transactions for subscriptions that span several regions, and this connection shapes how approvals, declines, and ongoing account management occur in practice. Research from the Bank for International Settlements shows that firms which coordinate these two areas report fewer mismatches between initial risk assessments and later account behaviors, while data from the same source indicates cross-border subscription volumes grew steadily through 2025 and into 2026.
Underwriting criteria typically include merchant category codes, expected transaction velocity, chargeback ratios, and geographic exposure limits, whereas support team protocols cover escalation paths, documentation standards, and response timeframes for customer inquiries. When these elements operate in isolation, discrepancies arise; when they connect through shared data feeds, the underwriting models receive real-time inputs that reflect actual customer interactions rather than static assumptions alone.
Core Components of Support Protocols in Subscription Environments
Support protocols in subscription settings often require agents to log every contact detail, including call duration, issue type, and resolution status, then route that information into centralized systems accessible to risk teams. Observers note that standardized logging practices allow underwriting systems to adjust exposure thresholds dynamically, especially when patterns such as repeated billing disputes appear across multiple regions. In September 2026 several processors implemented updated API connections that push support notes directly into underwriting dashboards, reducing the lag between customer contact and criteria revision from days to minutes.
Training modules for support staff now incorporate modules on data fields that matter most to underwriting models, and agents learn to flag indicators such as unusual payment method changes or requests for multiple billing address updates. Those who studied these programs report that the added context improves the accuracy of velocity checks and geographic risk scoring without extending average handle times.
Underwriting Criteria Across Multiple Regions
Multi-region underwriting requires criteria that account for differences in local regulations, currency volatility, and consumer protection rules. European Central Bank guidelines emphasize the need for consistent data capture on recurring payment authorizations, while similar frameworks in other jurisdictions require explicit consent records. Underwriters therefore maintain region-specific scorecards that weigh variables such as average ticket size, subscription length, and historical dispute rates against baseline thresholds that vary by market.
Linking these scorecards to support protocols means that when an agent in one region records a pattern of failed payment attempts followed by successful retries, that sequence feeds into the underwriting model for that merchant's entire portfolio. The result is an adjustment in reserve requirements or velocity limits that reflects actual behavior rather than projected figures.
Integration Mechanisms and Data Flows
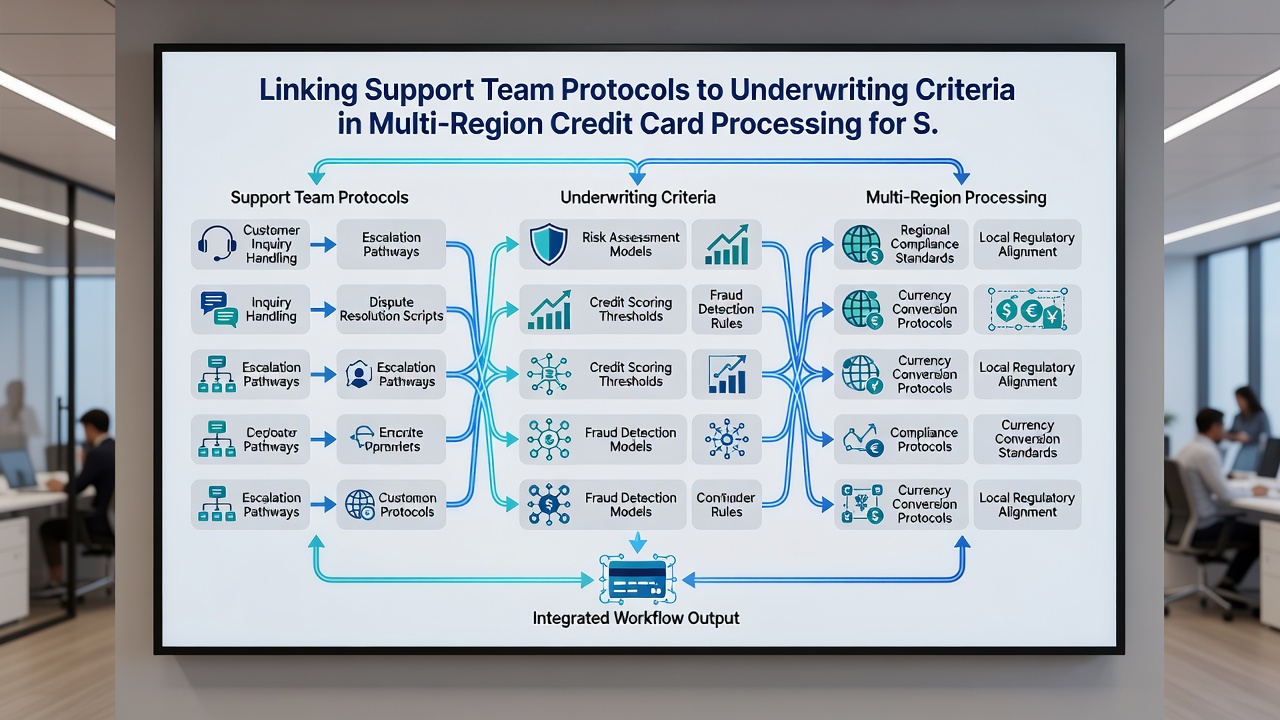
Integration typically occurs through shared databases or event-driven architectures that push support events into underwriting engines. One processor documented a 14 percent reduction in manual reviews after routing support interaction summaries directly to risk scoring algorithms. The architecture allows criteria such as maximum monthly volume to recalibrate automatically when support logs show elevated cancellation requests tied to billing clarity issues.
Another approach involves scheduled data pulls that aggregate support metrics weekly and feed them into underwriting recalibration cycles. Research indicates that organizations using weekly refreshes maintain tighter alignment between approved volumes and realized risk than those relying on monthly or quarterly updates alone.
Case Examples from Operational Settings
Take one subscription hardware provider that expanded from two markets to seven within eighteen months. Support teams in each new region followed identical logging standards, and underwriting models incorporated those logs to set region-specific hold percentages. Within the first quarter after expansion, the provider recorded a measurable drop in chargeback ratios compared with the prior period when support data remained siloed.
There's this case where experts found that merchants using automated alerts from support systems to underwriting teams could respond to emerging dispute clusters before they triggered broader criteria tightening. The alerts flagged merchants whose support tickets showed repeated references to unclear renewal terms, prompting underwriting to request updated disclosures before adjusting exposure limits upward.
Regulatory and Standards Context
Standards from the Consumer Financial Protection Bureau in the United States and the Australian Securities and Investments Commission both require documented processes for handling recurring payments, and these requirements extend to how customer service records inform risk decisions. Compliance teams therefore treat support protocol outputs as auditable inputs to underwriting criteria, ensuring that adjustments remain traceable during examinations.
Observers note that September 2026 saw several processors publish updated policy documents that explicitly describe the data handoff between support platforms and underwriting systems, reflecting increased regulatory focus on end-to-end process visibility.
Conclusion
The linkage between support team protocols and underwriting criteria produces measurable effects on approval accuracy, reserve calculations, and ongoing risk monitoring in multi-region subscription processing. Organizations that maintain continuous data exchange between these functions operate with criteria that reflect actual account activity across regions, while those that keep the areas separate encounter more frequent mismatches. Continued refinement of integration points, training alignment, and audit trails will determine how effectively the connection evolves as subscription volumes and regional requirements continue to shift.