Connecting Onboarding Procedures to Enhanced Detection Systems for Global Retail Payments
Ben Becker · Aug 5, 2026
Connecting Onboarding Procedures to Enhanced Detection Systems for Global Retail Payments
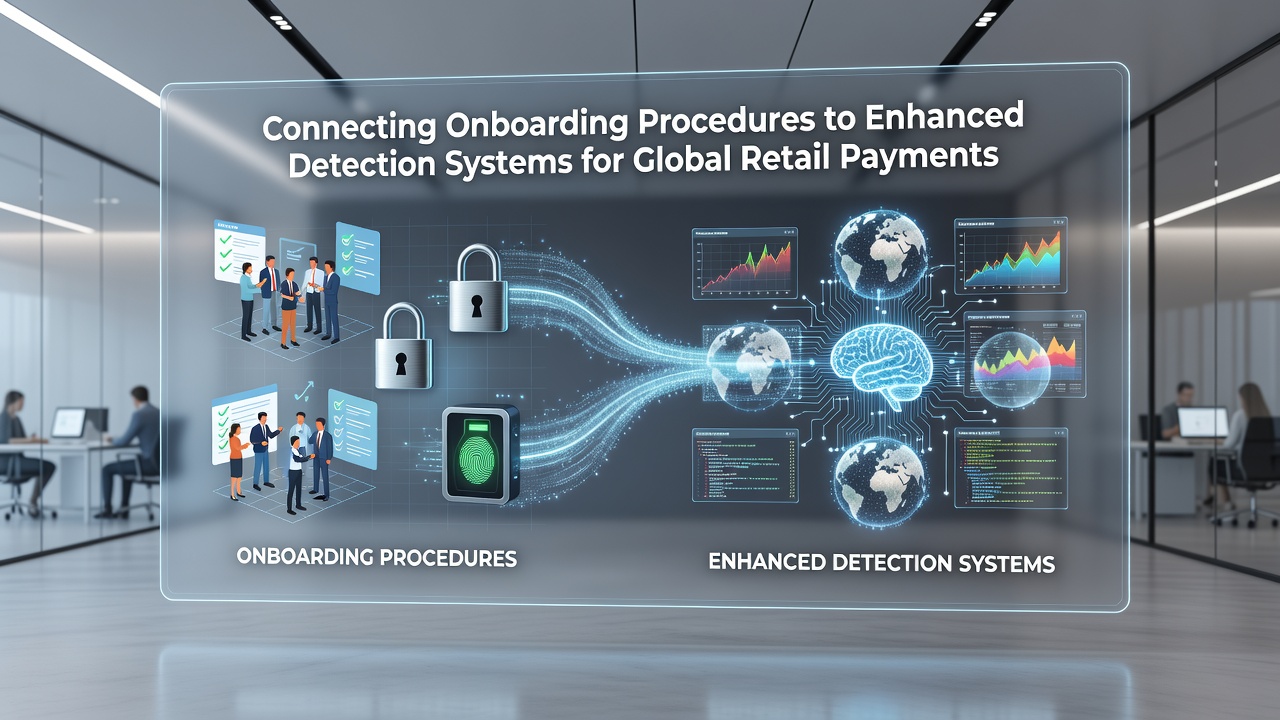
Retail payment networks have expanded across borders in recent years, and onboarding procedures now serve as the initial data collection point that feeds directly into detection systems. These procedures gather merchant details, transaction patterns, and verification records that algorithms later use to flag anomalies in real time. Observers note that when onboarding captures accurate information about business models and expected volumes, downstream systems gain clearer baselines for identifying deviations across multiple currencies and regions.
Core Elements of Onboarding in Retail Payment Flows
Merchants entering global networks complete identity checks, business registration reviews, and risk categorization steps that vary by jurisdiction. In practice these steps compile datasets on ownership structures, historical charge volumes, and geographic reach, which detection platforms reference when scoring new transactions. Research from the Bank for International Settlements indicates that standardized onboarding fields improve the precision of machine learning models deployed by processors handling cross-border traffic.
Integration occurs through shared databases where onboarding outputs populate risk profiles. A merchant approved in one market supplies address verification and bank account details that European and North American processors cross-reference against watch lists. This linkage reduces false positives because systems recognize expected activity ranges established during the initial review rather than treating every transaction in isolation.
Data Pathways Between Onboarding and Detection Layers
Once captured, onboarding information routes through secure APIs to fraud engines that apply rules based on velocity, device fingerprints, and counterparty behavior. Those who've studied these systems observe that enriched profiles allow models to distinguish seasonal retail spikes from suspicious spikes that lack corresponding business justification. In August 2026 several networks plan to introduce updated data schemas that require additional fields on recurring payment types, further tightening the connection between entry procedures and ongoing monitoring.
Global retail environments present added complexity because currency conversion and local regulations alter risk signals. Onboarding teams therefore document expected settlement currencies and tax identifiers, information that detection algorithms apply when evaluating whether a transaction aligns with documented patterns. Without these inputs, systems operating across Asia-Pacific and Latin American corridors generate higher volumes of manual reviews.
Regional Variations and Shared Standards
European frameworks under PSD2 emphasize strong customer authentication during onboarding, while Canadian guidelines focus on beneficial ownership disclosure. Both approaches generate structured data that processors in other regions can ingest. According to materials published by the European Central Bank, harmonized onboarding datasets have contributed to measurable declines in unauthorized transaction rates within participating networks.
Retailers operating subscription models or point-of-sale terminals in multiple countries benefit when onboarding records include projected transaction types and average ticket sizes. Detection systems then calibrate thresholds accordingly, limiting unnecessary blocks during peak periods such as holiday seasons. Studies conducted by academic researchers at the University of Melbourne have examined how these calibrated thresholds affect approval rates in cross-border retail environments.
Operational Outcomes Observed in Practice
Networks that link onboarding tightly to detection report fewer account takeovers because initial verification establishes trusted device and location baselines. Processors also note that merchants who supply complete documentation at entry experience faster resolution when anomalies arise, since analysts can reference the original risk assessment. Data from industry reports show that this continuity shortens investigation times by connecting early profile details with live transaction streams.
Hardware configurations and connectivity choices made during onboarding further support detection accuracy. Terminals configured to transmit location and firmware details provide additional signals that algorithms incorporate when assessing whether activity matches the merchant's declared operations. These technical linkages operate continuously once the merchant account activates.
Conclusion
The connection between onboarding procedures and enhanced detection systems rests on structured data transfer and consistent risk profiling. Retail payment participants across regions continue to refine these linkages through updated schemas and shared standards. As networks prepare for changes scheduled in August 2026, the emphasis remains on accurate initial data capture that strengthens real-time monitoring without disrupting legitimate transaction flows.